
Would You Let Your Parents Get Away With This?
Imagine your parents are approaching or already enjoying retirement. They have worked hard, raised a family and enjoyed a good standard of living. They own a nice home, have travelled, accumulated some retirement savings and quite reasonably want to enjoy the years ahead.
There is, however, a problem. Their income is no longer sufficient to support the lifestyle they have become accustomed to, but rather than adjusting their spending, they continue living well. They use some of their savings, draw down investments and perhaps borrow against their home. Over time there are fewer assets available to pass to their children, but their spending still exceeds their income.
So they borrow.
At first this doesn’t seem particularly concerning. They have assets, the bank is prepared to lend and everyone assumes their financial position will eventually improve. But each year the debt gets larger and, increasingly, so does the interest bill. Eventually they are borrowing not to build something new or create an asset, but simply to maintain the lifestyle they already have.
Meanwhile, their adult children are paying their own mortgage or rent, raising children, dealing with higher housing and living costs, trying to save for retirement and perhaps already helping their parents financially. They are effectively supporting three generations—their parents, themselves and their children.
When they finally confront their parents about the growing debt, they are told not to worry. The debt doesn’t really need to be repaid because it can simply be refinanced. Their assets should appreciate, incomes will grow and everything will eventually work itself out.
The children ask the obvious question: “What happens when you’re gone?”
The uncomfortable answer is that the debt doesn’t disappear. The financial consequences become somebody else’s problem.
Most of us would consider this an extraordinary way for a family to manage its finances. We would probably sit our parents down, look at their income and expenditure, discuss what they could realistically afford and make some difficult decisions.
So why don’t we ask similar questions about government?
Of course, the comparison is deliberately simplistic. The United States Government is not a household and sovereign finances operate very differently. But that doesn’t make the analogy irrelevant. In fact, it helps expose a much more important question about intergenerational fairness: to what extent should one generation be able to enjoy government expenditure and benefits without paying their full cost, while transferring part of that cost to generations that had no say in creating it?
When $40 trillion becomes meaningless
America’s gross federal debt has now passed $40 trillion. The problem with a number that large is that it becomes almost meaningless to an ordinary person. Whether somebody says $30 trillion, $40 trillion or $50 trillion, most of us cannot intuitively understand what any of those numbers represents.
A much simpler way of thinking about the current position is to look at the annual household budget. For fiscal 2026, the Congressional Budget Office projects federal revenue of approximately $5.6 trillion against spending of approximately $7.4 trillion, leaving a deficit of around $1.9 trillion.
Put into everyday language, for approximately every $100 the Federal Government receives, it spends around $132.
If your parents told you they earned $100,000 but were spending $132,000 every year and borrowing the difference, you wouldn’t need a degree in economics to recognise the problem. Your first question would probably be whether this was temporary. Perhaps there had been a medical emergency, a period of unemployment or some major investment that justified borrowing.
That is an important distinction because government borrowing isn’t inherently bad either. Borrowing during a recession, pandemic or war can be entirely appropriate. Borrowing to build infrastructure, fund productive investment, support research or increase future economic capacity can also leave the next generation with both the debt and valuable assets.
The concern with America’s current position is that these deficits are not projected to disappear when today’s circumstances pass. CBO projects continuing large deficits throughout the next decade, with the annual deficit reaching approximately $3.1 trillion by 2036. Debt held by the public is projected to increase from around 101% of GDP today to 120% in 2036, and under CBO’s longer-term projections to around 175% of GDP by 2056.
In other words, the family isn’t simply carrying a large mortgage. It is planning to add to the mortgage every year.
When yesterday starts consuming tomorrow
The most important number may eventually not be the debt itself, but the cost of servicing it.
CBO projects net federal interest expenditure increasing from approximately $1 trillion in 2026 to around $2.1 trillion by 2036. As that happens, an increasing proportion of government revenue becomes committed before governments make any new policy decisions.
This is where the family analogy becomes particularly useful. Imagine your parents telling you that a growing proportion of their retirement income isn’t actually paying for food, healthcare, travel or anything else they currently enjoy. It is simply paying interest on money they spent years earlier.
Government interest expenditure works in much the same economic sense. A dollar used to service accumulated debt cannot simultaneously employ a teacher, build a bridge, fund medical research, strengthen defence, reduce somebody’s tax bill or finance the infrastructure that might make the next generation more productive.
This is when yesterday starts consuming tomorrow.
The intergenerational equation is also changing
There is another dimension to this discussion that gets much less attention.
For many decades there has been an implicit intergenerational bargain. People work, accumulate assets, raise their children and eventually pass some of their accumulated wealth to the next generation. The next generation then repeats the process.
Longer lives are beginning to change that equation. Many retirees will quite reasonably use more of their accumulated wealth funding longer retirements, better lifestyles, aged care and increasingly expensive healthcare. Some will downsize or use home equity. Others will simply consume more of their retirement capital.
There is nothing wrong with that. It is their money and longevity is something society should celebrate.
But it has consequences.
A generation of children that might previously have expected some transfer of accumulated family wealth may receive less or receive it much later in life. At the same time, that generation is being asked to finance increasingly expensive housing, raise its own children, accumulate sufficient retirement savings for potentially longer lives and contribute through taxation toward Social Security, Medicare and the servicing of accumulated government debt.
This creates a potentially important combination: less private inheritance alongside greater public obligations.
Not every Baby Boomer is wealthy and not every younger person is struggling. There are enormous differences within generations, and it would be both inaccurate and unfair to turn this into an argument blaming older Americans. Many retirees have limited assets and depend heavily upon Social Security.
The more interesting issue is structural. What happens when the traditional transfer of accumulated private wealth between generations weakens at the same time that public financial commitments flowing in the opposite direction become larger?
That is the intergenerational question worth examining.
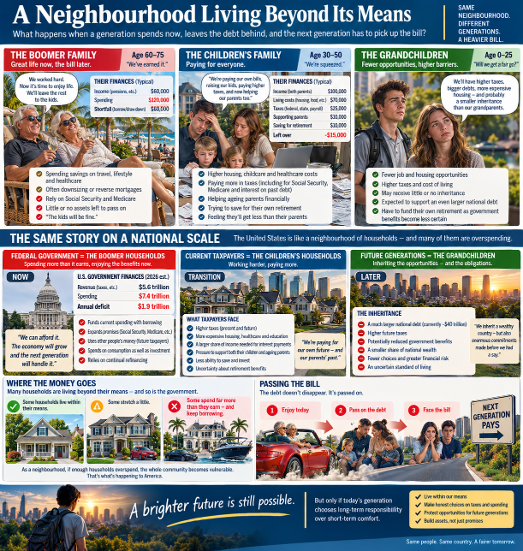
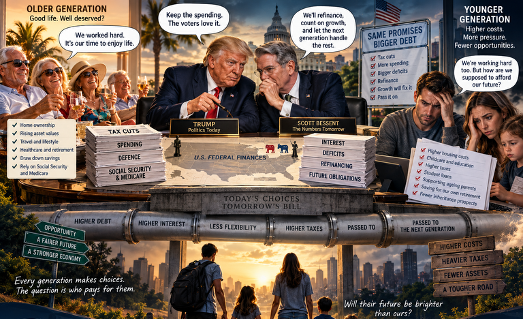
The Boomer household enjoys retirement and progressively consumes accumulated assets. The children’s household supports itself, its children and increasingly its parents. The grandchildren face higher barriers to accumulating assets of their own.
Beneath that sits the national equivalent: government borrows today, current taxpayers service the commitments and future taxpayers inherit whatever adjustment remains.
But America isn’t a household
This is where the analogy needs to be challenged, because there are significant differences between a family and a sovereign government. Ignoring them would make the argument much easier to dismiss.
| The criticism | Why it is correct | Why the analogy is still useful |
| Government isn’t a household | Government has taxation powers, monetary sovereignty and potentially perpetual existence. | These change how the burden can be distributed but don’t create unlimited real economic resources. |
| Government doesn’t have to repay all the debt | Treasury securities can continually mature and be refinanced. | Refinancing doesn’t eliminate the interest cost or the risk that future investors demand higher rates. |
| Children don’t literally inherit Treasury debt | Nobody receives an invoice for their share of $40 trillion. | Future citizens inherit the fiscal position and the taxation and expenditure decisions required to sustain it. |
| Government borrowing can create assets | Infrastructure, defence, education and research can benefit future generations. | This makes the distinction between borrowing for productive investment and borrowing for current consumption particularly important. |
| America owns enormous assets | It does, together with an extraordinarily productive private economy. | Many public assets aren’t readily saleable or income-producing. Sustainability ultimately depends on future productive capacity relative to future commitments. |
| Economic growth can solve part of the problem | Strong productivity and GDP growth can substantially improve debt sustainability. | Current CBO projections incorporate growth and nevertheless show debt increasing substantially relative to GDP. |
| Government can increase taxes | America retains substantial taxation capacity. | Higher future taxation is precisely one mechanism through which the adjustment can be transferred to future workers. |
| Government can create money | Monetary sovereignty provides options unavailable to a household. | Excessive monetary financing can transfer the adjustment through inflation and purchasing power rather than making the economic cost disappear. |
| Older Americans paid taxes themselves | Social Security and Medicare aren’t simply gifts from younger generations. | The systems nevertheless depend substantially upon current workers funding current beneficiaries, making demographics important. |
| Not all Boomers are wealthy | Many retirees have inadequate retirement assets. | The issue is the fiscal and political system, not the morality of a particular generation. |
The household analogy therefore shouldn’t be interpreted as saying “America is going bankrupt like Mum and Dad.” That isn’t the argument.
The relevant insight is simpler: resources consumed today ultimately have to come from somewhere. A sovereign government has many more mechanisms than a household for determining who bears that cost, but those mechanisms largely determine how the burden is distributed, rather than making it disappear.
Unfortunately, every solution creates another problem
There are solutions to America’s fiscal position. The difficulty is that there is no painless one, which probably explains why successive governments of both political persuasions have found borrowing politically easier than confronting the alternatives.
The most attractive answer is economic growth. If AI, automation, energy development, investment, innovation and productivity produce substantially faster economic growth, today’s debt becomes smaller relative to tomorrow’s economy. This should clearly be an important part of any solution. The problem is relying upon growth as the entire solution. CBO’s projections already assume continued economic growth and still show debt increasing significantly faster than GDP. Growth can make the adjustment considerably easier, but policymakers shouldn’t simply assume that future productivity will rescue decisions being made today.
The second obvious answer is reducing expenditure. Again, the arithmetic is straightforward but the politics are not. Cutting government bureaucracy and waste may be worthwhile, but the major long-term spending pressures include Social Security, Medicare, healthcare and interest. Eventually meaningful expenditure reform therefore involves difficult questions about eligibility, retirement ages, means testing, healthcare efficiency and the rate at which benefits increase. These are precisely the decisions politicians generally prefer not to put to today’s voters.
The third option is higher taxation. Additional revenue will almost certainly need to form part of any serious long-term solution. There are legitimate debates about higher taxes on wealthy households, corporate taxation, capital gains, closing loopholes and redesigning the tax base. But there is also a scale problem. If deficits remain sufficiently large, policymakers need to be honest about whether taxing a relatively small group of very wealthy people can fund all existing commitments indefinitely or whether the eventual tax burden would have to extend further into the broader population.
Tariffs can also produce substantial government revenue and may serve legitimate industrial, strategic and geopolitical purposes. But they are not free money provided by foreign countries. Some portion of their economic cost can flow through domestic prices, supply chains, investment decisions and reduced economic efficiency. Their fiscal benefit therefore needs to be considered alongside their wider economic effects. Higher tariffs can raise the cost of imported goods and inputs, with part of that cost ultimately flowing through to consumers and businesses as higher prices, potentially adding to inflation and reducing household purchasing power. They can also provoke retaliation, disrupt supply chains, reduce competition and investment, and weaken export opportunities—meaning the government may collect more tariff revenue while parts of the broader economy bear the cost.
Another possible adjustment occurs through inflation. Inflation reduces the real value of existing fixed nominal debt, but again the economic cost hasn’t disappeared. Cash savings lose purchasing power, wages may fail to keep pace with prices and future investors may demand higher interest rates to compensate for inflation risk. Wealthier households holding businesses, property and other real assets may also be better positioned to protect themselves than younger households dependent primarily upon wages. Resolving part of the debt burden through inflation can therefore have significant distributional consequences.
Finally, America can simply continue refinancing. There is no reason to assume the United States suddenly reaches $40 trillion, $45 trillion or some other arbitrary number and can no longer borrow. The United States possesses the world’s dominant reserve currency and the deepest sovereign bond market in the world.
The important question isn’t simply whether America can refinance.
It is at what price.
If investors increasingly require higher yields to hold Treasury securities, interest expenditure rises. Higher interest costs increase deficits, larger deficits require additional borrowing and additional borrowing adds to the debt stock. That creates the feedback loop that ultimately matters:
More debt → higher interest expense → larger deficits → more borrowing → more debt.
A fiscal problem therefore doesn’t necessarily arrive as a dramatic default or financial crisis. It can develop much more gradually as an increasing proportion of government revenue becomes unavailable for productive expenditure and each new government inherits progressively less fiscal flexibility.
The eventual answer is probably uncomfortable
The most realistic conclusion is that America will ultimately require some combination of most of these solutions.
Stronger productivity and economic growth will be essential. Government expenditure will need greater discipline. Social Security and Medicare will probably require reform. Healthcare needs to become substantially more efficient. Taxation and government revenue will likely need reconsideration. Retirement ages and eligibility arrangements may eventually need to reflect increasing longevity. Government benefits may need to become better targeted, and politicians may have to become much more disciplined about distinguishing borrowing for productive investment from borrowing simply to maintain current consumption.
None of those choices is particularly attractive.
But delaying them doesn’t eliminate them.
It changes who eventually has to make them.
So return to the family
Imagine the children finally sitting their parents down around the kitchen table.
They explain that Mum and Dad’s expenditure exceeds their income and ask whether they can spend less. The parents agree they could, but understandably don’t want to give up the lifestyle they enjoy.
Could the children contribute more? Yes, but that leaves less money for their mortgage, children and retirement.
Could the parents sell assets? Perhaps, although some assets are needed and others are already being progressively consumed.
Could everyone’s income grow sufficiently to solve the problem? Hopefully, but nobody can guarantee it.
Could the debt simply be refinanced? Certainly, although the family will continue paying interest and the eventual cost will depend upon future interest rates.
Could everyone simply ignore the problem and continue borrowing?
Probably—for quite some time.
The children eventually ask the most obvious question of all:
“Then why don’t we start fixing it now?”
And perhaps the most honest answer is:
“Because every solution requires somebody today to give something up.”
That is the real problem behind America’s $40 trillion debt.
It isn’t that the United States is about to run out of money. It isn’t that every American child will eventually receive an invoice for their share of the national debt. And it isn’t that sovereign finances operate exactly like a household budget.
It is that there is a growing bill, the cost of servicing it is increasing, and ultimately somebody bears the economic adjustment.
Every year that the current generation chooses not to decide who should pay, what should be reduced and what standard of living can sustainably be promised, more of that decision is transferred to people who had no say in creating the commitments.
Perhaps, therefore, we shouldn’t ask younger Americans whether they understand concepts such as debt-to-GDP ratios, primary deficits or Treasury refinancing.
We should ask something much simpler:
Would you let your parents get away with this?
If the answer is no, perhaps it is time to start asking the same difficult questions of the people managing your country’s finances.